
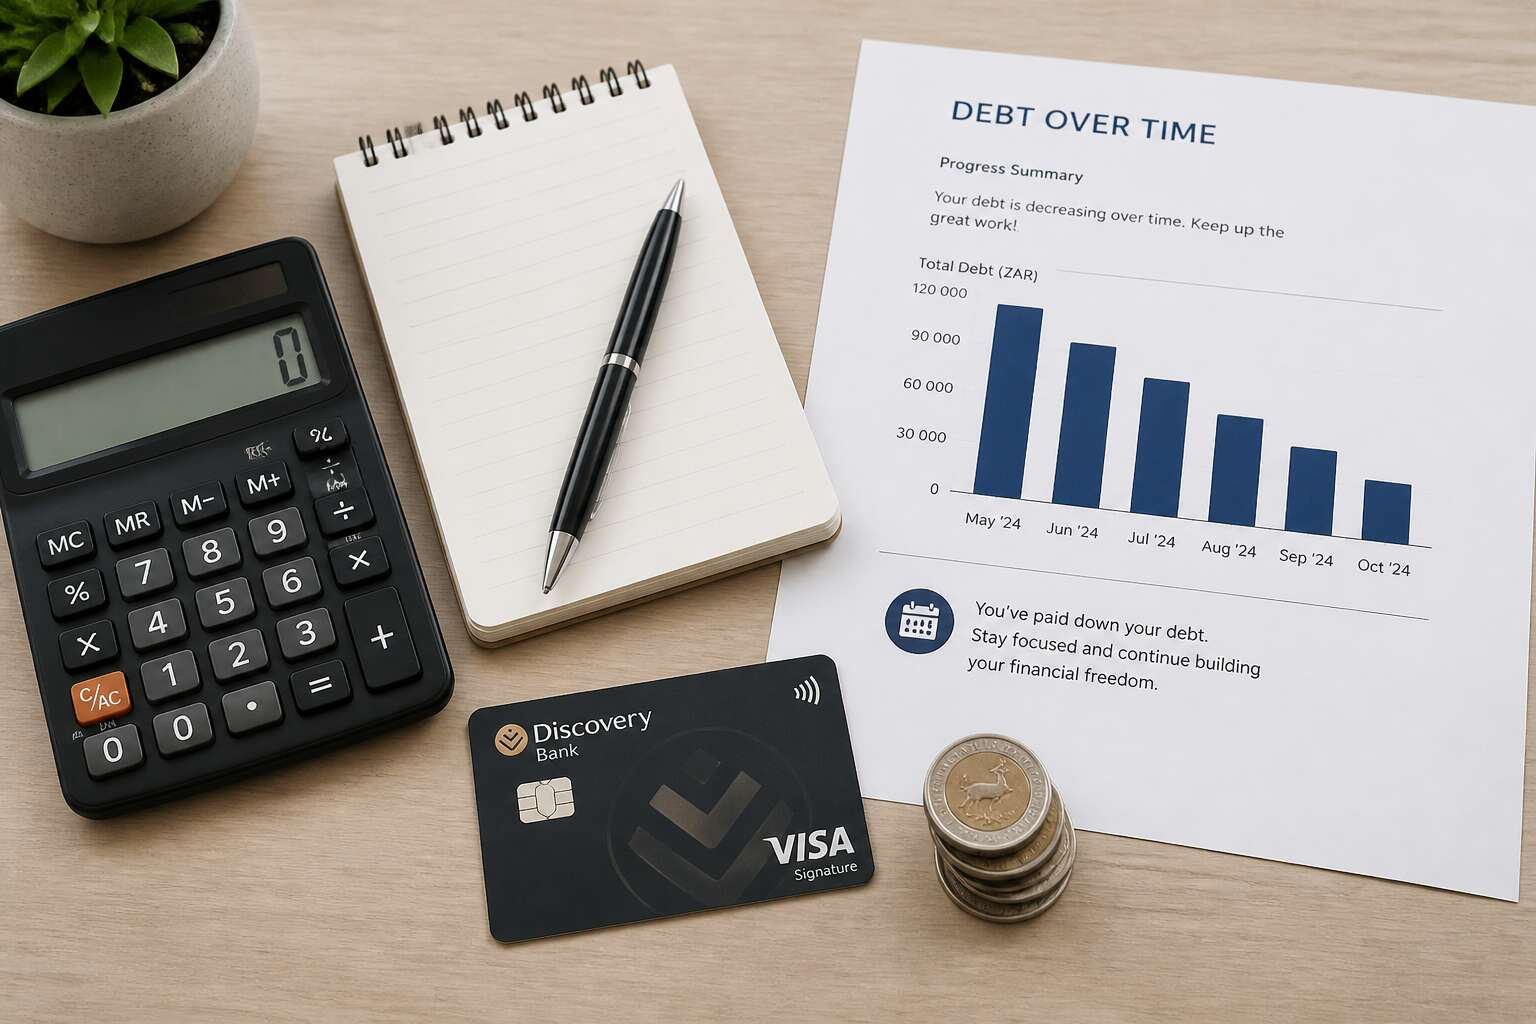
Understanding Debt Consolidation Options
What Is Debt Consolidation and How Does It Work?
Debt accumulates quietly, then demands attention. Understanding debt consolidation options begins with grasping the core mechanism. Debt consolidation discovery bank offers a pathway, merging multiple obligations into a single monthly payment. The process itself is surprisingly straightforward! You take one loan, settle your existing creditors, and face a solitary debt instead of many.
Interest rates determine whether this strategy works for you or against you. A lower rate reduces the total cost. A longer term lowers the monthly burden but extends the repayment period. These variables matter.
- One payment instead of several
- A single interest rate to monitor
- Clearer visibility of your financial position
The bank structures these loans with fixed terms, providing clarity. The mechanism is not magic. It is arithmetic applied to your obligations.
Key Benefits of Consolidating High-Interest Debts
Credit card interest in South Africa often exceeds 20% per annum. That is the enemy. Debt consolidation discovery bank replaces those punishing rates with a single, fixed figure. One payment, one deadline, one clear path forward. The arithmetic favors consolidation when your current rates outpace the new loan by several percent. Consider the tangible gains:
- Lower monthly pressure on your cash flow
- Reduced total interest over the life of the loan
- Predictable fixed installments
These factors matter for anyone juggling store cards or personal loans. I have seen how clarity transforms budgeting. The bank’s approach strips away confusion, leaving only a manageable obligation.
Comparing Personal Loans, Balance Transfers, and Home Equity
Consolidation isn’t a uniform process. Personal loans, balance transfers, and home equity each work differently. A personal loan from debt consolidation discovery bank provides a fixed rate and a set repayment schedule. Balance transfers shift existing debt to a new card with a low initial interest, though that rate rises later. Home equity uses your property’s value to secure a lower rate, but your home becomes collateral.
Consider these comparisons:
- Personal loans: steady monthly payments, no asset required
- Balance transfers: cheaper upfront, yet fees and rate hikes appear
- Home equity: low borrowing costs, but default risks your house
Discovery bank positions its personal loan as the primary debt consolidation discovery bank option. You replace several accounts with a single installment. The remaining options still have merit. Balance transfers suit short term gaps, while home equity works for larger debts. The details on fees, rates, and penalties often differ. I always look at the annual percentage rate before anything else. The right choice depends on your tolerance for risk and your repayment timeline.
How Discover Personal Loans Simplify Debt Consolidation
Key Features of Discover’s Debt Consolidation Loan
Carrying three separate debts means tracking three due dates, three interest rates, and three minimum payments. Discover’s debt consolidation loan reduces that burden to a single monthly installment. You borrow a fixed amount, pay off your creditors directly, and then focus on one repayment schedule. The loan’s fixed interest rate also protects you from the variable rate increases on credit cards.
Here are the features that make the process straightforward:
- Direct payment to creditors, so you never handle the funds yourself
- Fixed monthly payments that stay predictable for the entire term
- No origination fees or prepayment penalties
For South Africans juggling high-cost store cards and personal advances, this structure removes the guesswork. Debt consolidation discovery bank offers a clear path to regain control of your monthly cash flow.
Fixed Rates and Flexible Repayment Terms Explained
Most people expect their monthly payment to creep upward over time. A fixed rate loan stops that pattern. With debt consolidation discovery bank, your R1,400 monthly obligation remains R1,400 next year, not a guess based on prime rate movements.
Flexible repayment terms add control. You might choose a shorter term to clear the debt faster, or stretch the timeline to keep payments manageable alongside rent and school fees. I have seen borrowers choose both approaches, and each found relief in having a choice!
- Fixed rate removes the anxiety of variable interest rate hikes
- Repayment terms range from short to long, matching your budget
For South Africans, debt consolidation discovery bank offers a clear, steady path out of scattered debt. The fixed rate and flexible term work together, so you get certainty and choice in one simple loan.
Direct Payment to Creditors: Streamlining the Process
Handling three separate creditors means three due dates, three interest rates, and three calls when something slips. Direct payment removes that load. With debt consolidation discovery bank, the loan proceeds go straight to your listed creditors, not into your bank account. You receive one loan, and the lender handles the distribution.
That structure offers practical gains:
- No chance of diverting funds meant for debt
- Creditors see payment arrive on schedule
- You track a single monthly repayment
The result is fewer administrative tasks. No follow-up emails, no late fees from a forgotten date. The process becomes quieter, and you regain time to focus on your next financial step.
How Discover Compares to Other Leading Lenders
Consolidating debt should simplify your finances, not stretch them further. Discover personal loans achieve that by collapsing multiple creditors into a single payment. You pick a fixed term, lock in a stable rate, and watch the balance decline. The Discover platform handles every transfer, so your attention stays on one balance.
How Discover compares to other leading lenders comes down to a few practical points. Many banks charge setup fees or impose hidden penalties. Discover does not. The application takes ten minutes, and the rate you see is the rate you keep. I have compared lenders across the market, and these three attributes stand out:
- No origination fees, ever!
- Direct payment to creditors without intermediaries.
- A grace period for late payments without penalty.
For a South African borrower, the debt consolidation discovery bank offers a clear advantage: simplicity without surprises. That is what separates it from other personal loan providers.
Eligibility and Application Process for a Consolidation Loan
Credit Score Requirements and What to Expect
Most people imagine a debt consolidation discovery bank application requires a flawless credit score, but the truth is more pragmatic. While a score above 660 improves your odds, Discover looks at your entire financial picture, including your debt to income ratio and payment history. They want to see stability, not perfection.
The application itself is refreshingly brisk. You start online with a pre qualification step that uses a soft credit pull, so your score takes no hit. What a relief that is! If you proceed, a hard inquiry appears, but that is a small price. Before you start, gather these items:
- Your latest payslips or proof of income
- A list of creditors and their outstanding balances
- Your South African ID or passport
Expect a decision within a few days, sometimes hours. The entire process for debt consolidation discovery bank feels less like an interrogation and more like a straightforward transaction. Just ensure your documents are accurate, because in my experience, a missing payslip slows everything down faster than load shedding.
Step-by-Step Guide to Applying Online with Discover
Applying for a debt consolidation discovery bank loan is a bit like assembling flat pack furniture: intimidating until you see the instructions. Eligibility requires a steady income, a South African ID, and a debt to income ratio that doesn’t make underwriters wince. Once you clear that bar, the online application takes minutes.
Here is the step by step:
1. Visit Discover’s website and select the consolidation loan option.
2. Use the pre qualification tool, which does a soft credit pull.
3. Upload your payslips, creditor balances, and ID.
4. Review the loan offer, then approve the hard inquiry.
Within days, funds head to your creditors directly. Just double check your documents. One misplaced payslip turns a snappy process into a waiting game. That is the only real snag.
How to Calculate the Right Loan Amount for Your Needs
Eligibility for a debt consolidation discovery bank loan comes down to three things: a steady income, a valid South African ID, and a debt-to-income ratio underwriters accept. The application process begins with the prequalification tool and its soft credit pull. Once you review the loan offer and approve the hard inquiry, creditor statements and payslips are verified. One misplaced document resets the entire timeline!
To calculate the right loan amount for your needs:
- Gather every unsecured debt balance and its interest rate.
- Sum those balances to establish your baseline.
- Add the loan’s initiation fee and monthly service charges.
- Subtract any payment you can make from savings, keeping your emergency fund intact.
Borrowing only the amount that settles those debts keeps your term short. A larger loan extends repayment and inflates total interest, which defeats the purpose of consolidating with debt consolidation discovery bank.
Common Reasons for Loan Denial and How to Improve Approval Odds
The underwriter’s gaze lingers on every blemish. For a debt consolidation discovery bank loan, eligibility requires a steady income, a valid South African ID, and a debt-to-income ratio that does not curdle. Prequalification performs a soft credit pull, a mere whisper. Approving the offer triggers the hard inquiry, and then the real scrutiny begins. Creditor statements and payslips must align perfectly. One misplaced document resets the entire timeline!
Denial usually stems from these recurring failures:
- Unstable employment that raises suspicion.
- Debt-to-income ratios above the lender’s threshold.
- Errors or gaps in the submitted paperwork.
Approval odds deepen when documents verify themselves. Clean payslips, a consistent work history, and a settled debt-to-income ratio signal reliability. The debt consolidation discovery bank process rewards patience and precision, not haste.
Managing Your Finances After Consolidating with Discover
Building a Debt Repayment Plan That Actually Works
Approval is the easy part. The genuine test begins once the money moves. After your debt consolidation discovery bank loan settles your old accounts, your monthly payment shifts to a single lender. Your spending habits remain unchanged unless you adjust them deliberately. I have watched borrowers, post consolidation, quietly rebuilding the same balances.
A repayment plan needs structure. Here is what I recommend:
- Track every expense for thirty days before setting your budget
- Allocate a specific amount for discretionary spending, not a vague category
- Schedule your payment the day after your salary lands
Build a buffer for unexpected costs. Discover’s fixed rate keeps your payment steady, making this planning simpler. Each month without carrying a new balance strengthens your position.
Strategies to Avoid Rebuilding Credit Card Debt
Once your debt consolidation discovery bank loan clears your old accounts, one monthly payment remains. Your credit cards sit empty. That quiet period is where many borrowers stumble. The crisis feels finished, and spending creeps back without conscious effort.
In my experience, borrowers who succeed watch for the early signs:
– The takeaway coffee you skipped before
– The online cart that checks out without hesitation
– The budget category that quietly stretches
Your fixed Discover rate keeps the monthly amount stable. That stability gives you room to observe your own behaviour. Notice where money flows when nobody is forcing you to account for it. Each month without carrying a new balance strengthens your position.
The single payment to debt consolidation discovery bank becomes the only debt you carry. Guard that arrangement closely.
Using a Debt Consolidation Calculator for Long-Term Planning
After the loan clears your old accounts, the quiet of a single monthly payment can feel strange. I have found that a debt consolidation discovery bank calculator gives the clearest view of what comes next. It shows total interest, payoff date, and the effect of paying extra each month.
Your fixed rate keeps the payment steady, but the timeline still shifts with your choices. Run the numbers quarterly. The calculator reveals:
- Your payoff date under the current schedule
- The interest saved by rounding payments up
- How a side income shortens the loan term
That discipline keeps the debt from returning.
When to Choose a Balance Transfer Card Instead of a Personal Loan
Once the debt consolidation discovery bank loan settles your accounts, the real work begins. A balance transfer card tempts with a zero percent intro rate, but that window closes faster than a Johannesburg summer thunderstorm. Personal loans from debt consolidation discovery bank offer fixed terms, which suits those who prefer certainty over a countdown clock.
Consider a balance transfer only if you can clear the balance before the promotional period ends. Otherwise, the residual interest defeats the purpose. The loan route rewards consistency, while the card route rewards speed. Most households need the former.
- Transfer fees add up quickly
- Missed payments cancel the promo rate
- Your credit utilisation shifts monthly
Choose based on your temperament, not the marketing.
Pros and Cons of Using Discover for Debt Consolidation
Advantages: No Fees, Rate Discounts, and Strong Customer Support
Discover’s debt consolidation offering avoids the usual friction points. No origination fees, no late penalties, and no annual charges. I have seen borrowers assume these costs are unavoidable, yet Discover proves otherwise! Consider the advantages:
- Zero fees mean every rand of your loan goes toward principal.
- The autopay discount lowers your APR by 0.25%.
- 24/7 customer service simplifies coordinating creditor payments.
The drawbacks are fewer but real. Approval requires a solid credit history, and the APR range may exceed local credit unions. The debt consolidation discovery bank experience remains compelling for borrowers who value transparency. The absence of hidden costs creates a predictable path when your budget is already tight.
Potential Drawbacks and How to Mitigate Them
Credit requirements for the debt consolidation discovery bank loan remain the most significant barrier. I have seen borrowers with steady incomes get declined because their score did not meet the threshold. Even approved applicants may see an APR that exceeds the rates offered by South African credit unions, which undermines the zero fee advantage.
Mitigation is not a trick but a process. A credit score improves over consecutive months of on-time payments. Applicants who rush the timeline often discover that the waived fees cannot compensate for a higher interest cost.
- Strict minimum credit score thresholds
- Debt-to-income ratio limits
- Loan amount caps for new customers
These constraints shape the overall experience. Borrowers who understand them can decide whether to wait, adjust loan size, or look elsewhere.
Realistic Expectations for Approval and Funding Timelines
Approval for a debt consolidation discovery bank loan rarely arrives overnight. Underwriting typically takes two to five business days, and funding can stretch another week. South African applicants, used to face to face branch lending, often underestimate that gap.
The pros carry weight: zero origination fees, fixed rates, and direct creditor payments. The cons demand honesty: credit thresholds remain steep, and the disbursement pace lags local micro lenders. I have watched borrowers grow restless during that quiet window.
Expect this sequence:
- Application review within 24 hours
- Income and debt verification
- Funding three to seven days after approval
That timeline assumes every document arrives clean! Missing payslips stall the process.
0 Comments