
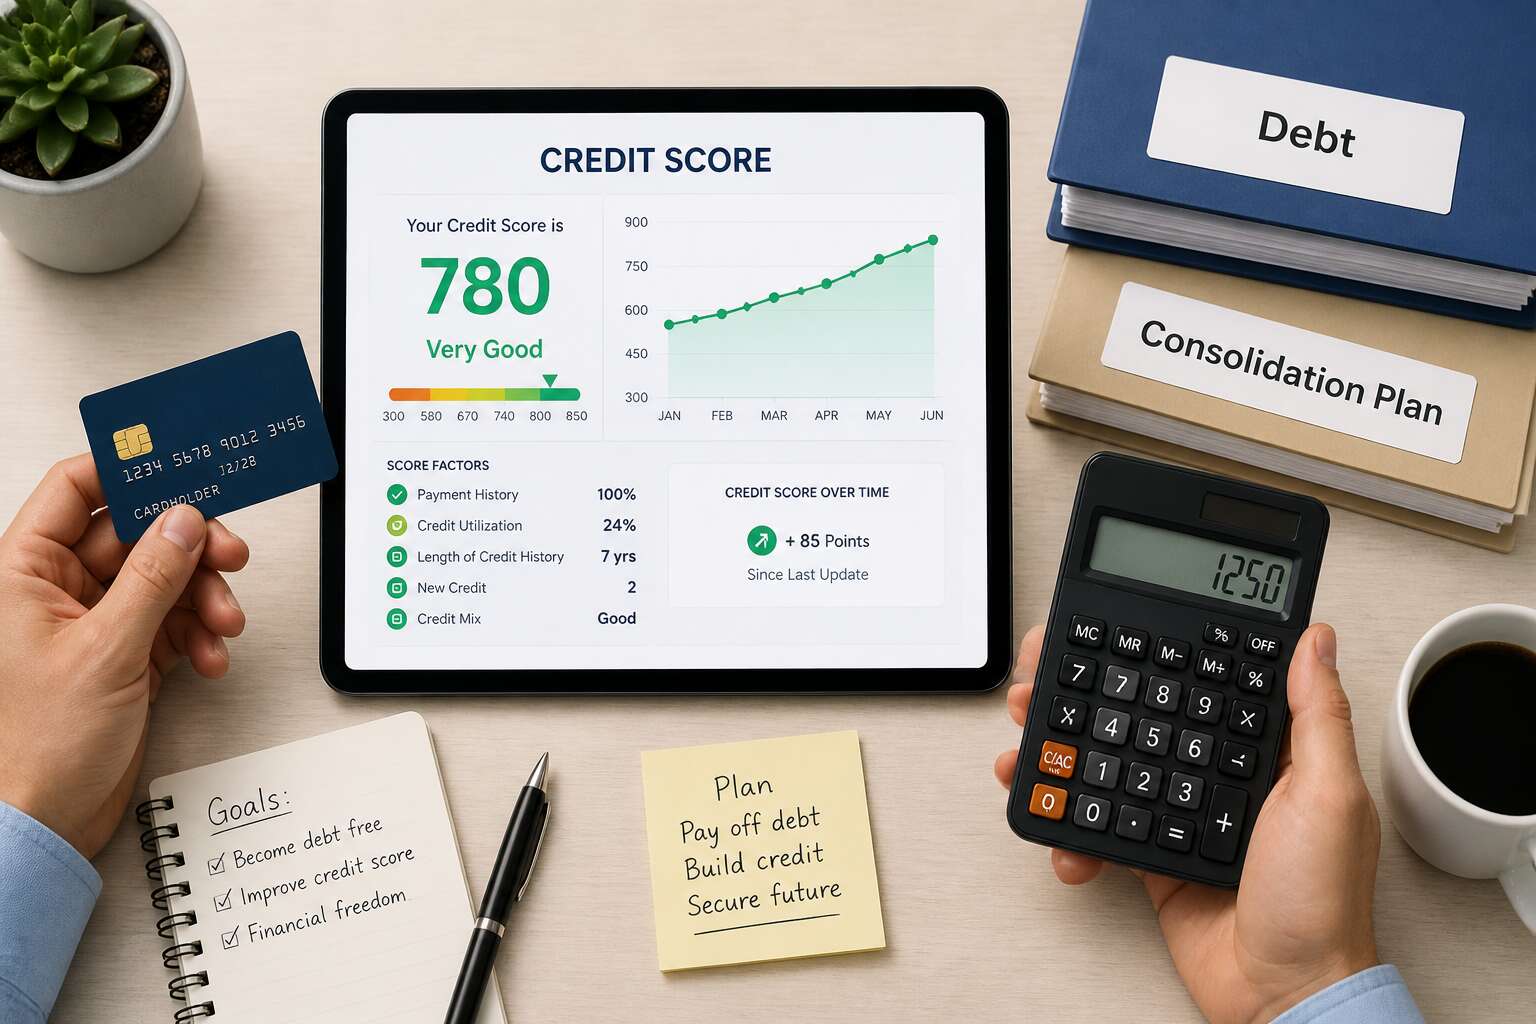
Understanding Debt Consolidation
What Is Debt Consolidation?
Debt consolidation combines multiple debts into a single new loan. You pay off existing creditors and then owe one lender. This simplifies your monthly payments and often lowers your interest rate. The credit bureaus watch this process closely, from the initial application to your ongoing payment behaviour.
Will debt consolidation affect my credit? It depends entirely on the method you choose! The main approaches include:
- Personal loans paid directly to creditors
- Balance transfers to a new card
- Debt management programmes
Each option carries its own credit implications. A loan application triggers a hard inquiry, which affects your score briefly. Closing old accounts changes your credit utilisation ratio. The determining factor is your payment history.
The Mechanics of Credit Reporting
The real drama of consolidation plays out in your credit report, a ledger where your financial discipline is perpetually on trial. It is not a simple subtraction of your old balances, but a complex re-evaluation of your reliability as a borrower. The most immediate tremor is the hard inquiry, a confirmation that you are actively seeking new credit, which can momentarily shave a few points off your score.
Yet, the deeper mechanics involve a shift in your credit utilisation ratio. When you take out a personal loan to settle credit cards, your revolving utilisation drops dramatically, a move that tends to please the scoring algorithms. However, a new instalment loan adds to your total debt picture, which can offset some of those initial gains. For a fleeting moment, your credit history shows a new line, a zeroed-out card, and a fresh monthly obligation, a period of transition that requires patience.
Consider what the bureaus are actually observing during this transition:
– The lifespan of your oldest account may be affected if you close the cards you just paid off.
– The mix of credit types changes, adding an instalment loan to your revolving credit cards.
– Your payment history, the most significant weight in your score, is reset to a new baseline.
– The balance transfer to a new card might provide a temporary buffer of low utilisation.
The psychology here is about trading the chaos of many due dates for the singular weight of one. A balance transfer does not erase the debt, it merely relocates it. The credit card issuers will still calculate your utilisation across your available limits, and if you max out that new card, your score will suffer just as much as it did with the old ones. The most profound effect, however, is the pattern of your payment behaviour, which is the only narrative that truly dictates your financial reputation.
Hard Inquiries vs. Soft Inquiries
Before you panic about applying for a consolidation loan, know the difference between a hard inquiry and a soft inquiry. A soft inquiry happens when you check your own score, or when a lender peeks at your report for pre-approval purposes. It has zero effect on your credit! A hard inquiry happens when you formally apply for credit, and the lender digs through your full history to decide whether to trust you with their money.
- Soft inquiries appear only on your personal report and never influence scoring.
- Hard inquiries are visible to other lenders and can temporarily lower your score by a few points.
Most debt consolidation applications trigger hard inquiries. The question will debt consolidation affect my credit deserves a nuanced reply: yes, slightly, but only for a short window. Scoring systems treat multiple applications within a short period as one inquiry, which reduces the impact.
Debt-to-Income Ratio and Credit Utilization
Two figures carry more weight than any late payment on your path to consolidation: your debt-to-income ratio and your credit utilisation. I have seen borrowers fixate on their score while ignoring these deeper metrics. Here is how they shift when you consolidate:
– Debt-to-income ratio compares monthly obligations to gross income. A consolidated payment below your old combined payments lowers this ratio.
– Credit utilisation measures revolving balances against limits. Moving card debt to an instalment loan reduces this percentage sharply.
Lenders view a ratio above 40% as risky, yet a single consolidation can pull it below that threshold. Utilisation drives up to 30% of your score, so freeing capacity rewards you quickly.
So will debt consolidation affect my credit? It does, but through predictable channels. When both ratios improve, your score often climbs within a few months.
Immediate Credit Score Changes
Why Your Score Might Drop Initially
Your credit score does not enjoy surprises. When you consolidate, a fresh loan account lands on your report, and the scoring engine immediately recalculates. The question of will debt consolidation affect my credit gets a short, honest answer: yes, at first, it can nudge your score downward before any long term gains appear.
The main reason is account age. A new consolidation loan lowers the average age of your credit accounts. At the same time, the old accounts you pay off stop reporting positive payment history. Those two changes often happen in the same month, which creates a double hit. Your score may also slip because the model treats recently opened credit as a temporary risk. A typical initial drop looks like this:
- New credit line: minor penalty for recent borrowing.
- Closed old accounts: loss of their established history.
- Updated balances: the model recalculates your overall exposure.
The Role of Credit Utilization
Within a month of consolidation, your credit file performs a quiet routine refresh. Balances are settled, new terms appear, and the scoring engine recalculates its view of you. The immediate shift is rarely dramatic, but it is always present. I have seen borrowers lose five points while others lose twenty. The difference often comes down to how your utilization behaves after the dust settles.
Credit utilization measures the gap between your revolving limits and what you owe. When consolidation pays off credit cards, those cards report a zero balance. That can suddenly lift your utilization ratio. However, the new installment loan sits in a separate category. It does not count toward utilization. This separation matters for your immediate score because the algorithm treats revolving debt far more critically than installment debt.
- Revolving accounts: now at zero or reduced balance
- Installment accounts: new loan reported with full balance
- Scoring model: utilization base shifts entirely
So to answer the question will debt consolidation affect my credit, yes, but the effect is temporary and closely tied to how utilization recalculates. The score you see in the first week is not the score you will carry into the next statement cycle.
How Long the Dip Lasts
Your first post consolidation statement is the real test. The zero balances land, but the algorithm takes time to adjust. In my experience, the immediate shift can be as little as four points or as much as twenty. The direction depends on what remains on your cards.
Most South African borrowers see the dip flatten by the second billing cycle. Hard inquiries lose their sting after thirty days. The new installment account stops being a fresh entry and starts building history. So when someone asks will debt consolidation affect my credit, the honest answer is yes, but briefly.
Consider the typical timeline:
1. Week one: score drops five to fifteen points.
2. Month two: utilization settles, score recovers.
3. Month four: on time payments push the score above the starting point.
That dip is temporary. Your next payments shape the story!
Long-Term Credit Impact After Consolidation
Recovering Your Score With On-Time Payments
The months after consolidation carry a strange tension. Your score sits low, yet every payment is quietly rewriting your financial story. I have seen this pattern repeat across hundreds of credit files. The question, will debt consolidation affect my credit, stops being a worry and becomes a reference point.
Payment history dominates this phase. Each on-time installment deposits positive data. After a year, lenders see consistency. After two years, they see a borrower who recovered. One missed payment disrupts that narrative.
The recovery is gradual but measurable. Your score after consolidation improves with every due date you honour. That is the entire mechanism. No mystery remains once you understand it.
The Effect of Closing Old Accounts
Closing old accounts after consolidation triggers a slow migration in your credit file. Those accounts do not vanish overnight! They linger, still holding weight in your credit age calculation. Over time, they age out and your consolidated loan becomes the primary reference point.
So, will debt consolidation affect my credit in the long run? I have watched this play out many times. Yes, but the effect is structural rather than dramatic:
- Closed accounts remain on file for years in South Africa
- Their contribution to account age diminishes gradually
- The consolidation loan seasons and assumes the dominant position
The balance between these factors determines your long-term trajectory. A well-managed consolidation loan becomes a stable anchor, while the closed accounts fade into background detail.
Building Positive Payment History
Ask the question long after the paperwork is done, and the answer changes. In the long term, will debt consolidation affect my credit? Yes, but the effect tilts positive once your payment history takes the lead.
The consolidation loan becomes the primary reference point in your file. Each monthly instalment, recorded correctly, builds a track record that gradually outweighs the closed accounts. The loan seasons.
Here is what happens during the seasoning period:
- The loan age increases steadily
- Closed accounts lose relevance gradually
- The credit mix shifts toward instalment debt
As months pass, the old accounts linger, but the loan carries your history forward. Steady payments become the foundation. That is the long-term answer.
When to Expect Significant Improvement
Time reveals the true answer to whether will debt consolidation affect my credit. After six months of consistent payments, your file starts to shift. The consolidation loan now dominates your credit profile, and each on-time instalment adds weight.
Expect meaningful improvement between nine and eighteen months! Lenders see a borrower managing a single loan responsibly. The scattered balances that once dragged you down are gone.
- Month six: initial recovery from the hard inquiry dip
- Month twelve: clear positive trajectory in your score
- Month twenty-four: the loan becomes a mature credit account
Beyond that, the long-term effect solidifies. So will debt consolidation affect my credit? Yes, but with patience, the answer becomes increasingly favourable.
Monitoring Your Credit Progress
Most South African consumers ask will debt consolidation affect my credit before they take the leap. The short answer is that the long-term horizon holds the real reward. After the two-year mark, the consolidation loan becomes a mature account. This permanence signals stability to credit bureaus. The positive trajectory continues, though the pace slows. Lenders see a fiscal record free from scattered retail debt. This is where you want to be.
Monitoring your progress is not a passive act. You should review your credit report every few months. Look for the specific markers that indicate your consolidated loan is working for you.
– A steady decline in your credit utilisation ratio.
– No new hard inquiries on your file.
– A consistent payment history logged for the loan.
These markers clarify the narrative on your file. You can also track your credit score through your banking app. Some providers offer free monthly statements. Comparing these reports shows the arc of your fiscal health. So, will debt consolidation affect my credit? Yes, and the true answer emerges in the long game. Your patience and consistent behaviour craft a story that future lenders will read favourably.
Comparing Consolidation Methods and Their Credit Effects
Balance Transfer Credit Cards
A 0% balance transfer is tempting, but the fine print decides your credit future. Balance transfer credit cards let you move high-interest debt onto one card at a promotional rate, often 0%. This can save thousands if you pay off the balance in time.
Will debt consolidation affect my credit? Yes, but the mechanics differ from other methods. The transfer triggers a hard inquiry, costing a few points. The new card increases your total available credit. Keep old accounts open and your credit utilization ratio drops, helping your score.
Balance transfers carry specific risks:
- The promo rate expires, exposing you to standard interest.
- Transfer fees, typically 3% to 5%, increase your balance.
- Closing old accounts shrinks available credit and hurts your score.
South African lenders watch repayment patterns. A late payment on the new card erases progress. So will debt consolidation affect my credit? It depends on your discipline.
Debt Consolidation Loans
Debt consolidation loans replace revolving debt with an installment obligation. This shift matters because South African credit bureaus weigh revolving and installment debt differently. A personal loan, even at a lower interest rate, changes your credit mix and can signal stability to lenders. The question of will debt consolidation affect my credit becomes a matter of perspective: the loan creates a new payment schedule, one with a definitive end date.
Unlike a balance transfer, a consolidation loan pays off creditors directly. Your cards remain at zero, but the loan balance appears on your profile. The psychological effect is quieter. You trade many small pressures for one larger, structured commitment. The credit score reflects this trade. Will debt consolidation affect my credit? Yes, through the introduction of a new installment line and the reduction of available revolving credit.
- The loan principal is fixed, so monthly payments are predictable.
- Your utilization on existing cards drops to zero, which improves that ratio.
- The loan term, often 12 to 60 months, defines the recovery window.
The discipline required is identical to any consolidation path, but the mechanics are distinct. The score responds to the new account and the closed cycle of revolving debt.
Home Equity Loans or HELOCs
Home equity loans and HELOCs present a different trade. These options secure the consolidation against your property, which shifts the risk profile entirely. South African credit bureaus treat secured debt as a distinct category. Will debt consolidation affect my credit through a home equity loan? Yes, because a new secured installment line replaces your revolving debt. Your credit card utilisation drops to zero, often improving that ratio. However, the loan adds a significant obligation to your profile.
Consider the structural differences:
– A home equity loan provides a fixed lump sum with a fixed repayment term, similar to a personal loan.
– A HELOC acts as a revolving facility, so your utilisation ratio remains a moving target.
The score reacts differently to each. A fixed loan signals predictable repayment. A HELOC behaves like a credit card, meaning the balance you draw influences the utilisation calculation. The answer to will debt consolidation affect my credit depends on which structure you select.
Debt Management Plans
Debt management plans operate differently from loans and balance transfers. A credit counselling agency negotiates with your creditors to restructure payments, often securing interest rate reductions. The credit bureaus record these negotiated terms distinctly. Some South African lenders treat a “concessioned” account as a risk signal rather than a relief.
Consider how this affects your utilisation ratio. A consolidation loan closes revolving accounts and replaces them with one installment, improving the ratio. A debt management plan leaves the balances on the original cards, so the ratio stays unchanged. Will debt consolidation affect my credit when you choose a management plan? The answer depends entirely on the mechanism you select.
- A consolidation loan creates a new account and lowers utilisation.
- A debt management plan preserves existing accounts and their balances.
- Neither method erases the underlying debt from your profile.
Student Loan Consolidation
Student loan consolidation follows its own logic. When you merge study loans into one facility, the new account carries a fresh date, but the credit bureaus retain the original account history. This differs from a balance transfer, which creates a new revolving line.
Will debt consolidation affect my credit when the loans come from a single institution? Your lender may restructure the loan internally, leaving your credit file unchanged. Other banks open a new account and close the old ones, which temporarily reduces your average account age.
The reporting nuances matter:
– The outstanding balance stays identical, yet the utilisation ratio may improve if the loan converts to an installment type
– Your payment history transfers, so a single late study loan payment remains visible
– The new repayment term could extend by years, which some South African credit providers interpret as increased risk
The real answer to will debt consolidation affect my credit with student loans arrives in the months after consolidation. As the new repayment pattern forms, your profile gradually adjusts. The old accounts vanish, but the history lingers on your report.
Credit Counseling and Its Reporting Effects
In South Africa, the choice between consolidation methods often comes down to which credit rating impact you can tolerate. The answer to will debt consolidation affect my credit depends entirely on the instrument you select. A consolidation loan replaces several accounts with one installment line. Balance transfers create revolving utilization shifts. Each method alters your file differently.
Credit counseling follows a different reporting path. The counselor negotiates with creditors without opening new accounts or closing old ones. Your report reflects the resulting payment arrangements, but the original account ages stay intact. This makes counseling appealing if you want to avoid fresh hard inquiries altogether.
Key reporting differences:
- Counseling rarely triggers new account openings.
- Debt management plans may show as third-party arrangements.
- Consolidation often closes old accounts and starts new ones.
The direct answer: will debt consolidation affect my credit more visibly than counseling? Generally, yes.
Protecting Your Credit Score During the Process
Prequalify With Soft Credit Checks
With the spectre of a credit score dip looming, many South Africans hesitate before consolidating. The primary question, will debt consolidation affect my credit, often stops people from exploring viable solutions. The answer is nuanced. A clear distinction exists between a hard search and a simple rate check.
Prequalify with soft credit checks to see your options without harming your file. This process uses an informational inquiry, which is invisible to lenders. It leaves no trace. When you finally apply, only the formal credit agreement triggers a hard search, and that impact is temporary.
Before you commit, remember these three points:
– Confirm that the lender uses a soft check for prequalification.
– Ensure you are comparing truly personalised rates, not just generic quotes.
– Prepare your supporting documents so the final application is a single, clean event.
You retain control if you verify each step. Unnecessary applications burden your history. A single strategic move preserves your standing while you still get the benefit of lower interest rates.
Keep Credit Card Balances Low
Consolidation gives your finances a moment of stillness, but the work does not end with the new loan. The immediate question of will debt consolidation affect my credit shifts once you start managing daily spending again. The temptation to use that now empty credit card is real, and giving in erases your progress.
Those cards remain open on your file. Their limits still count toward your total available credit. If you run up a new balance while paying off the consolidation loan, your utilization ratio climbs again. Lenders see a person who solved one problem by creating another. The credit bureaus see the same thing.
Protecting your score during this phase requires a simple discipline:
– Leave the old cards at home, not in your wallet.
– Pay for new purchases with cash or a debit card.
– Set a monthly reminder to check that the old balances stay at zero.
This is ordinary behaviour, but it is also the difference between a temporary dip and a long term failure. You worked hard to secure a lower interest rate. Do not hand that advantage back to the bank through careless spending. The answer to will debt consolidation affect my credit is largely written by your next six months of behaviour. Keep the balances low, and the report shows a borrower who learned the lesson.
Avoid Opening New Credit Accounts
Opening a new store card or personal loan while your consolidation is still reporting feels like progress. It is the opposite. Every application triggers a hard inquiry. That inquiry lands on your file alongside the new consolidation account. Lenders in South Africa see a borrower who is still hungry for credit. The score sees a risk.
The will debt consolidation affect my credit question depends on how many new accounts you add. One inquiry costs a few points. Three or four, combined with a fresh account, can slow your recovery entirely. The new account also lowers your average account age, which carries weight in scoring models. A thin file suffers more than an established one.
Let the consolidation loan stand alone. Old cards remain open. New credit waits until the loan is paid. That restraint is what ultimately answers will debt consolidation affect my credit in your favour.
Set Up Automatic Payments
Setting up automatic payments for your consolidation loan is the single strongest shield you can raise over your credit score during this period. The will debt consolidation affect my credit question becomes far less daunting when you remove human error from the equation. A single missed payment can trigger a default listing that stays on your South African credit bureau file for years, long after the initial score dip from the consolidation itself has healed.
Automatic debit orders ensure your monthly instalment leaves your account on the exact date your lender expects it. This consistency builds a pristine payment history, which is the heaviest weight in most scoring models. You are effectively telling the bureau that you can manage this new debt responsibly.
Here is what a reliable setup involves:
1. Check your bank account balance before the debit order date each month.
2. Set an alert for two days before the payment is due.
3. Keep a buffer amount in the account to cover unexpected charges.
Many South African banks allow you to schedule these alerts through their apps, turning a passive process into an active one. The will debt consolidation affect my credit narrative changes entirely when every payment lands on time, without you lifting a finger. You build momentum, and that momentum translates into a score that climbs steadily rather than stuttering.
0 Comments