
Understanding the Core Approaches
South Africans are drowning in debt. The latest numbers show household debt to disposable income remains staggeringly high. When the walls close in, two lifelines appear. But they are not the same. They lead to different destinations, and choosing wrong can worsen your financial torment.
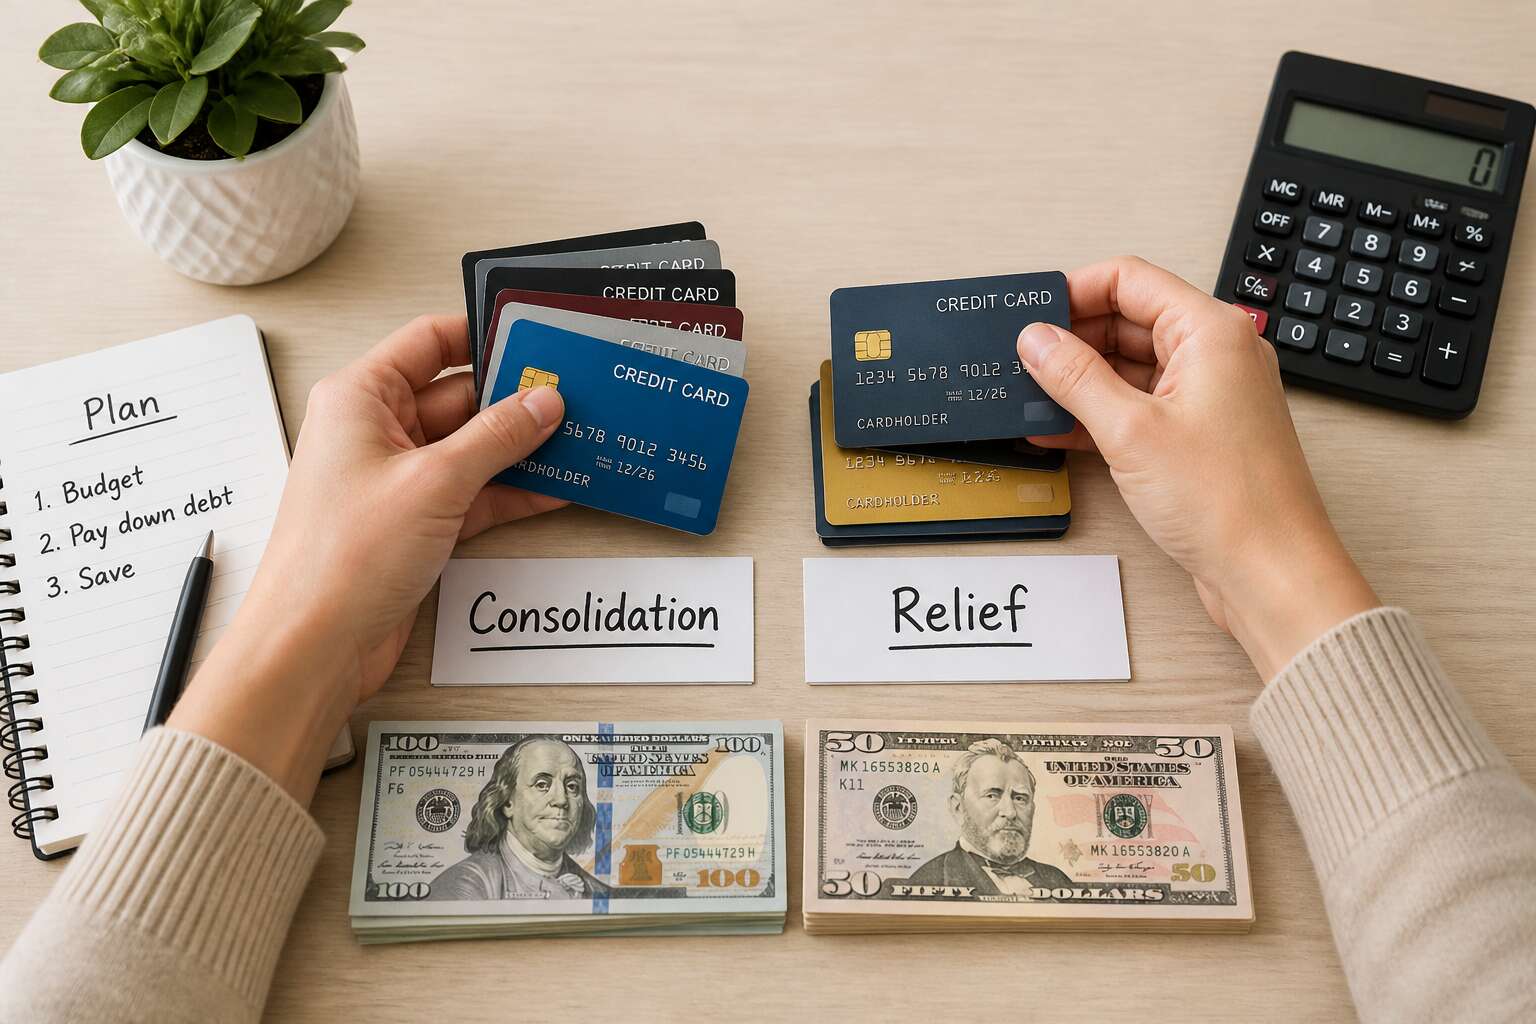
Debt consolidation versus debt relief is a comparison of outcomes, not just terms. Consolidation takes your scattered debts and merges them into a single monthly payment. It is a restructuring of chaos. Relief, on the other hand, negotiates to reduce the actual principal you owe. It is a confrontation with creditors, often involving a debt review process that impacts your credit profile for years. One preserves your record; the other sacrifices it for a fresh start.
The weight of interest compounds the pressure. With consolidation, you still repay the full capital. With relief, you settle for less, but the damage to your credit score can haunt your applications for new accounts or home loans. Your choice dictates whether you face slow recovery or a longer, more visible financial shadow.
Evaluating Financial Impact and Eligibility
Forty percent of South Africans are over-indebted, per the National Credit Regulator. Choosing between debt consolidation versus debt relief is a serious choice. Consolidation merges debts into one loan, often at a lower rate. Relief asks creditors to accept less than you owe. Eligibility depends on how severe your debt is.
Credit score, income stability, and asset ownership matter. Consolidation rewards a decent score. Relief targets demonstrable hardship. The financial impact varies. Consolidation reduces monthly payments but keeps the full balance. Relief shrinks the balance but damages your credit profile.
Relevant factors include:
- Debt-to-income ratio
- Total unsecured debt
- Credit score range
- Employment history
A consolidation loan often yields lower interest. Relief can erase a portion of principal. The choice rests on your long-term goals and current credit standing.
Comparing Long-Term Consequences
Comparing long-term consequences reveals how debt consolidation versus debt relief shapes your future. Consolidation merges payments, keeping your credit score intact, but it extends the interest you pay over many years. Relief reduces what you owe, yet it leaves a settlement marker that stays on your record for half a decade.
Consider these differences:
- Consolidation often means higher total interest, though steady monthly costs.
- Relief might clear your debt sooner, but future lenders will hesitate.
I have seen this in Johannesburg. One friend chose consolidation and still pays a decade later. Another took relief and struggled to get a home loan. The real cost is not the monthly figure; it is the long-term credit history.
Choosing the Right Path for Your Situation
Almost every week, I meet someone who is drowning in monthly repayments, yet firmly believes all financial remedies are the same. They are not. The real distinction between debt consolidation versus debt relief is not about semantics, but about your long term financial trajectory. Consolidation is a rearrangement of debt, a single monthly payment that pulls your creditors into one line. Debt relief, however, involves a negotiation to reduce the actual amount you owe, which is a far heavier legal hammer.
This decision rarely hinges on numbers alone. It hinges on discipline. If your income is steady and your problem is simply that too many dates fall in the same week, consolidation is a quiet, orderly path. But if you are dodging creditor calls or your property is at risk, you need the statutory protection that formal relief provides.
For those considering the latter, the process is not a casual chat. It involves:
– A full assessment of your assets and liabilities
– A legal process that requires a court order
– The appointment of a debt counsellor or administrator
– A strict budget that removes your access to credit
The irony is that you must surrender control to regain it. I have seen people choose consolidation because they fear the stigma of debt relief, only to hold onto a repayment that steals their salary for a decade. Others rush into relief without realising that their credit record will carry a mark for years.
Take stock of what you are truly trying to save. A credit score is a tool, not a trophy. The question is whether you value your immediate cash flow or your future borrowing power. Sequestration is a dramatic step, and administrative receivership is not a light switch. Neither is a simple consolidation loan.
The answer is rarely found in a spreadsheet alone. It is found in an honest appraisal of your spending habits and your capacity to stick to a plan. Are you the type to refinance your home because a holiday is due? Then consolidation is a trap. Are you willing to hand over your cards and live on a strict allowance? Then relief might set you free. Choose accordingly.
Common Pitfalls and Practical Considerations
Debt consolidation versus debt relief often sounds straightforward on paper, but the real world is messier. I have seen people consolidate unsecured loans into a home bond, only to lose the roof over their heads. That is the trap of secured debt. The pitfalls are rarely visible at the start. Interest rates shift, fees sneak into the fine print, and your credit score takes a knock before it improves.
Practical considerations demand you read every clause. Here is what commonly trips people up:
- Transferring balances without checking the initiation fee.
- Ignoring how long the new term actually stretches.
- Assuming relief means a clean slate, when it often means damaged credit.
You need to compare apples with apples. A lower monthly payment can hide a longer repayment period. Debt consolidation versus debt relief is not a choice between good and bad, it is a calculation of your own discipline and risk tolerance.
0 Comments